
NAICOM boss Identifies Weak Corporate Governance, Others as Challenges to Insurance Industry.
By Ewache Ajefu
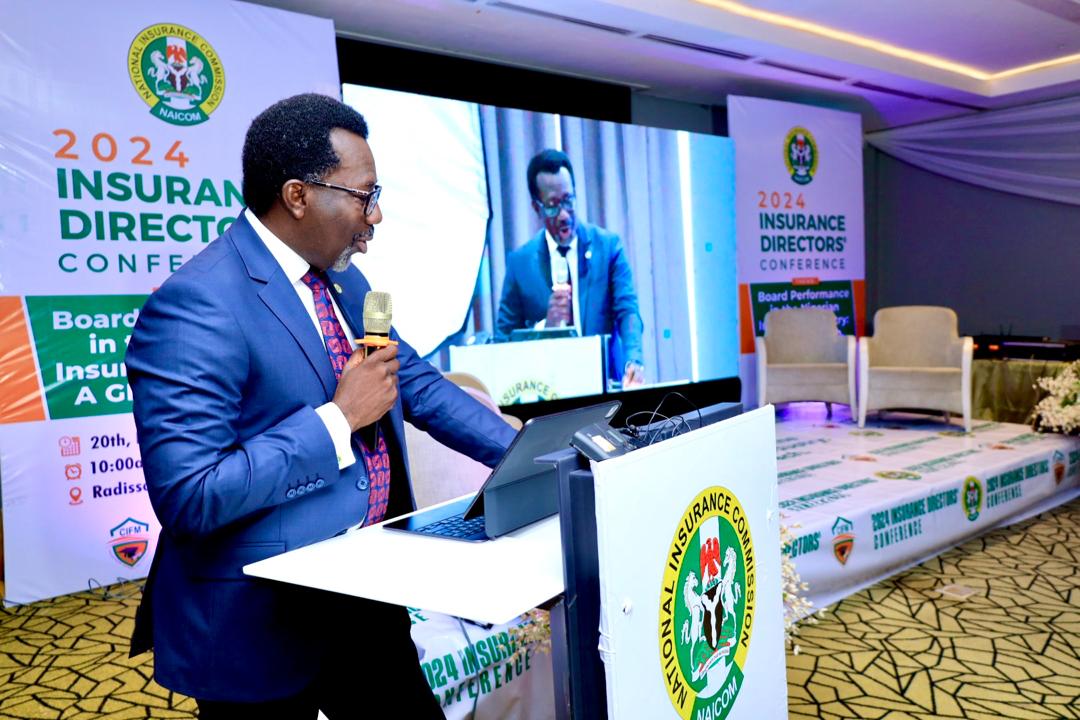
Commissioner for Insurance and Chief Executive officer of National Insurance Commission(NAICOM), Mr Olusegun Ayo Omosehin has identified weak corporate Governance practices, poor risk management and very low compliance culture as challenges to the Nigeria Insurance Industry.
Mr Omosehin stated this in his opening remarks at the ongoing 2024 Insurance Directors Conference Wednesday in Lagos.
He said to overcome these challenges, the Board as the highest policy making organ for the various institutions must demonstrate genuine commitment and strict adherence to Governance, Risk, and Compliance principles.
According to him, if carefully implemented, this will improve decision-making, increase transparency and accountability, and ultimately improve regulatory compliance.
The NAICOM noted that the 2024 Insurance Directors’ Conference is crucial in setting the agenda for the insurance industry where strategic leadership issues in the sector would be discussed, focusing on navigating complexities and ensuring sustainability.
He said that the theme for this year’s conference “Board Performance in the Nigerian Insurance Industry: A GRC Approach” focusing on the performance of the Board and the critical role of Governance, Risk and Compliance principles, could not have come at a better time.
He posited that in today’s global business landscape, integrating GRC at the Board level is vital for business success and sustainability, as ot is no longer optional, but an essential ingredient for enhancing decisionmaking, transparency, accountability and risk management.
He said effective GRC ensures that Boards have the necessary tools to make informed decisions, identify potential risks, and maintain the highest standards of compliance.
He noted that NAICOM is committed to aligning the insurance sector with the President’s goal of growing the Nigerian economy to USD$1 trillion by 2030, and achieve this, the commission is committed to creating the necessary regulatory framework required to achieve meaningful contribution from the insurance sector, adding that de-risking a trillion-dollar economy takes more than mere rhetorics.
He further said the Commission is fully committed to working with the National Assembly in delivering the required legal and regulatory framework which would flow from the successful passage of the 2024 Insurance Reform Bill.
He said the Commission has set 5 key priorities that will deliver on this agenda:
safeguard policyholders and improve confidence in the insurance industry,
Strengthening supervisory capabilities, Improve safety and soundness of our institutions, foster Innovation and sustainability of the insurance industry and
enhancing overall insurance accessibility and penetration in Nigeria.
He said the Commission’s primary focus is on ensuring timely payment of genuine claims and expect all insurers to significantly reduce their outstanding claims by the end of the year, as emphasized during the last Insurers Committee meeting, adding that indue delays in the settlement of genuine claims will no longer be tolerated.
He noted that the Commission is committed to strictly enforcing the law and taking swift action against any insurer failing to meet their claim obligations, stressing that “if a company cannot honor legitimate claims, it has no place in our industry”.
He added that the financial stability and soundness of our institutions are now more vital than ever, stressing that to remain relevant and competitive, “our institutions must comply with all the relevant prudential regulations and requirements”.
According to him, “We must begin to prepare our various entities well ahead of the Risk-Based Capital regime, so ensuring adequate capitalization is no longer optional. We must prioritize robust capitalization to effectively tap into target markets and navigate current industry realities”.
He said the Commission in the last one and half years have successfully examined a few of our institutions using the Risk Based Supervision Approach, even though the exercise has not been fully completed.
He however sought the cooperation of the gathering as Directors of insurance institutions and demand compliance on issues that have been raised and directed to the various Boards, for attention.
He urged the Directors as policymakers across institutions to develop and implement policies that promotes adherence to good governance, effective risk management and compliance principles.
He said the goal of the Commission is to ensure sustainability, securing the long-term viability and future resilience of insurance entities.